If you are researching how to negotiate a total loss payout for hail damage, the most useful answer is the one that separates what is technically possible from what is financially or practically sensible. Small details such as paint condition, local rules, temperature, material or policy wording can completely change the right choice.
This guide focuses on the decision points that matter in real ownership, not viral shortcuts or one-size-fits-all claims. You will see where a DIY step is reasonable, where documentation matters and where a professional or state-specific answer is safer.
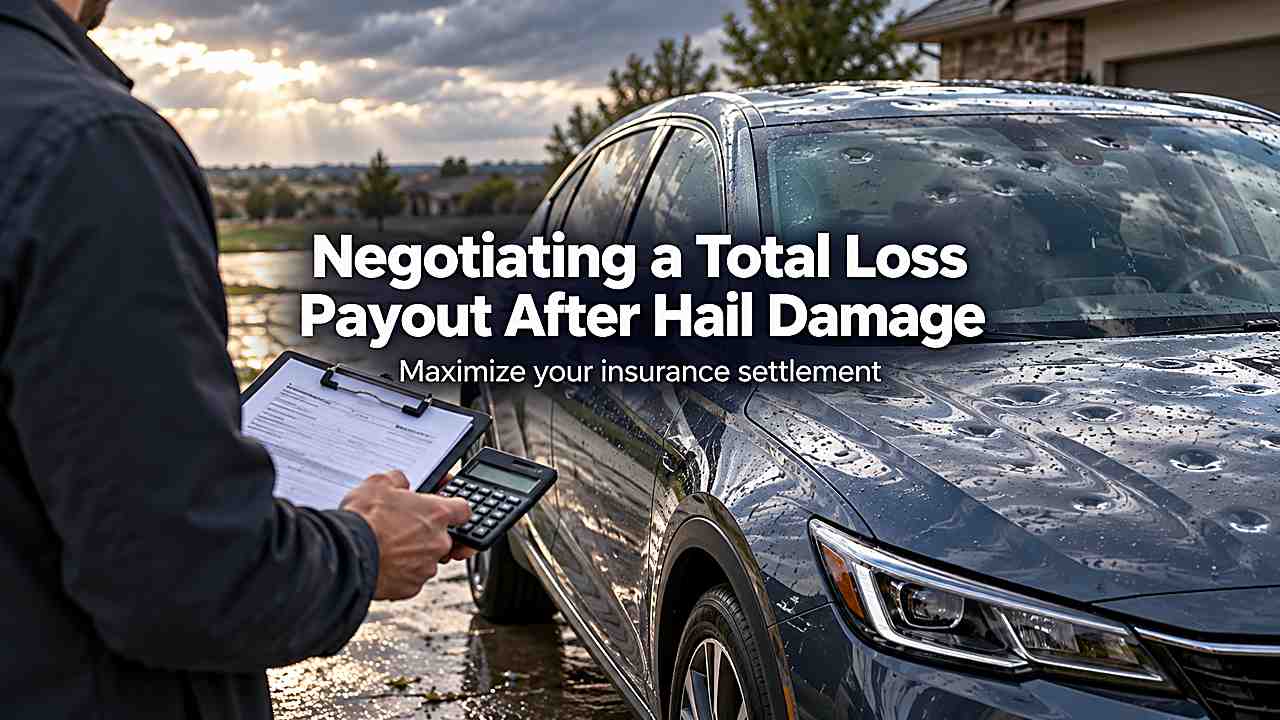
You can challenge a hail total-loss valuation by checking the insurer’s vehicle description, correcting mileage and option errors, documenting pre-loss condition and presenting genuinely comparable local vehicles. The goal is not to demand an arbitrary number; it is to show why the actual cash value should be different.
Understand what you are negotiating
In this article, understand what you are negotiating matters because it changes the practical decision in ways that are easy to miss from a quick glance. The details below show what you should verify before you spend money, alter the surface or assume two similar-looking situations need the same solution.
The settlement is based on pre-loss actual cash value, not your loan balance
Actual cash value is intended to reflect what the vehicle was worth immediately before the hail loss. The insurer may use a third-party valuation report, comparable vehicles and adjustments for mileage, condition and equipment. What you paid years ago and what you still owe are separate numbers. Negotiating effectively starts with the valuation evidence, not the monthly payment.
When you evaluate the settlement is based on pre-loss actual cash value, not your loan balance, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
The deductible and lien payoff are separate from the valuation
If the ACV is $18,000 and your comprehensive deductible is $1,000, the gross valuation and net claim payment are different. A lender may also receive payment first. Do not argue that ACV is wrong simply because the loan payoff is higher. Gap coverage, if applicable, addresses a different problem.
When you evaluate the deductible and lien payoff are separate from the valuation, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Audit the valuation report line by line
In this article, audit the valuation report line by line matters because it changes the practical decision in ways that are easy to miss from a quick glance. The details below show what you should verify before you spend money, alter the surface or assume two similar-looking situations need the same solution.
Verify the exact trim, drivetrain, options and mileage
A missing premium package, incorrect engine, wrong drivetrain or mileage error can materially affect value. Check VIN-decoded equipment against the report. Also verify body style and major factory options. Send correction requests in writing with supporting documents or photos.
When you evaluate verify the exact trim, drivetrain, options and mileage, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Review condition adjustments against the car you actually owned
Insurers may adjust for interior, exterior or mechanical condition. If the report marks the car below average but you have recent photos, service records and receipts showing unusually good condition, provide them. Maintenance does not always add dollar-for-dollar value, but it can support condition. Focus on evidence that differentiates your car from the assumed baseline.
When you evaluate review condition adjustments against the car you actually owned, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Build a credible comparable-vehicle set
In this article, build a credible comparable-vehicle set matters because it changes the practical decision in ways that are easy to miss from a quick glance. The details below show what you should verify before you spend money, alter the surface or assume two similar-looking situations need the same solution.
Match year, trim, mileage and market area as closely as possible
A higher-priced vehicle is not a useful comparable if it has a different trim, much lower mileage or expensive options. Gather several listings that resemble your car before the hail event. Note dealer versus private-party status. Consistency across multiple comparables is stronger than one unusually expensive ad.
When you evaluate match year, trim, mileage and market area as closely as possible, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Account for advertised price versus actual transaction value
Listings show asking prices, not necessarily final sale prices. The insurer may adjust them, and that can be reasonable. Your argument should focus on whether the insurer selected inferior comparables or made unsupported adjustments. A well-matched local set is more persuasive than simply citing a national price guide.
When you evaluate account for advertised price versus actual transaction value, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Check taxes, fees and state-specific settlement items
In this article, check taxes, fees and state-specific settlement items matters because it changes the practical decision in ways that are easy to miss from a quick glance. The details below show what you should verify before you spend money, alter the surface or assume two similar-looking situations need the same solution.
Some states require sales tax or certain transfer fees in a total-loss settlement
The exact treatment varies by state and may depend on whether you replace the vehicle. California guidance, for example, requires certain taxes and fees in a fair total-loss settlement, while other states use different rules. Ask for an itemized settlement. If a required fee is missing, point to the state rule rather than treating it as a discretionary bonus.
When you evaluate some states require sales tax or certain transfer fees in a total-loss settlement, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Owner-retained salvage changes the net payment
If you keep the hail-damaged car, the insurer typically deducts salvage value from the settlement. Title branding and inspection rules then depend on state law. Get the salvage deduction in writing before agreeing. Keeping the car can be economical, but only after you understand registration, financing, insurance and future resale consequences.
When you evaluate owner-retained salvage changes the net payment, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Use escalation tools carefully
In this article, use escalation tools carefully matters because it changes the practical decision in ways that are easy to miss from a quick glance. The details below show what you should verify before you spend money, alter the surface or assume two similar-looking situations need the same solution.
Ask the adjuster to reconsider before invoking a formal dispute process
Send a concise package that lists each factual error, your supporting documents and your comparable vehicles. Ask how the company responds to valuation disputes. Many disagreements are resolved when the data is corrected. Emotional arguments about attachment to the car do not establish market value.
When you evaluate ask the adjuster to reconsider before invoking a formal dispute process, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Read the appraisal clause and state complaint process if disagreement remains
Some policies provide an appraisal process for disputes over amount of loss, and states also offer insurance-department complaint channels. The exact rights and deadlines vary. For a large gap, legal or professional valuation advice may be worthwhile. Use formal processes only after you understand their costs and scope.
When you evaluate read the appraisal clause and state complaint process if disagreement remains, treat it as one part of the decision rather than a shortcut. Compare it with the condition of your vehicle, the limits of the product or repair method, and any manufacturer, insurer or local requirements that apply before you move to a more aggressive step.
Prepare a valuation packet that an adjuster can actually review
Put your evidence into a short organized package rather than sending a stream of unrelated screenshots. Start with a cover note listing the valuation errors you found. Then include the VIN or build sheet for missing options, a mileage photo if the report is wrong, pre-loss condition photos, relevant service records and three to five close local comparables. Highlight the specific difference each item supports. This makes your request easier to evaluate and keeps the discussion focused on actual cash value.
Avoid inflated comparables that are obviously different from your car or listings hundreds of miles outside the normal market unless the vehicle is unusually rare. A credible dispute is built on consistency. If the insurer rejects an adjustment, ask which evidence it relied on and whether the policy offers an appraisal process. The stronger your documentation, the less the conversation depends on subjective statements about what the car was worth to you personally.
Know the difference between a factual correction and a valuation opinion
A factual correction is straightforward: the report lists the wrong mileage, misses all-wheel drive, identifies the wrong trim or describes the interior as poor when recent photographs show otherwise. Those issues can be supported directly with documents. A valuation opinion is more subjective, such as arguing that one dealer listing proves every comparable should be worth the same amount. Start with factual corrections because they are the easiest for an adjuster to verify.
Then address comparables systematically. Explain why a listed vehicle is not comparable if it lacks a major package, has dramatically different mileage or is outside the relevant market. If the insurer makes condition or mileage adjustments, ask how they were calculated. You are more likely to improve the offer by identifying a measurable valuation problem than by simply asking for a higher number.
Before a final agreement, ask for a written breakdown showing gross ACV, deductible, taxes or fees, lien payoff, salvage deduction if you keep the car and the resulting net payment. These numbers answer different questions and should not be blended together. If the gross value is fair but the net check looks low, the cause may be the deductible or loan rather than an undervalued vehicle. Understanding that distinction keeps your negotiation focused on items that can actually be corrected.
Frequently Asked Questions
These questions address the issues that most often cause confusion around how to negotiate a total loss payout for hail damage. They are useful for checking your plan before you spend money, alter the vehicle or rely on a rule that may not apply to your exact situation.
Can I negotiate a total-loss offer without hiring a lawyer?
Yes. Many valuation disputes involve factual corrections and better comparables rather than legal issues. Start by requesting the full valuation report and documenting specific errors. If the dispute becomes large or involves legal interpretation, professional advice can be appropriate.
The most reliable answer comes from the specific vehicle and documentation rather than an internet average. Keep photos, estimates and policy or product paperwork when they affect the decision.
Does KBB determine what the insurer must pay?
No single price guide automatically controls actual cash value in every state. Insurers often use local comparable vehicles and third-party valuation systems. A guide can be supporting evidence, but stronger evidence usually comes from closely matched local vehicles and accurate condition data.
You do not need to solve every variable yourself. A qualified repairer, glass shop, insurer or state regulator can confirm the details that are specific to your situation.
Can recent repairs increase my total-loss payout?
Routine maintenance usually helps prove condition but does not add its full cost to market value. A recent major component replacement may matter more, depending on the vehicle and local market. Provide receipts and let the valuation process determine the adjustment. Do not assume a $2,000 repair adds $2,000 to ACV.
If your vehicle, policy or product falls outside the normal case, verify the exact instructions before acting. That extra check is especially worthwhile when the downside includes paint damage, broken glass or a disputed claim.
What if my loan is higher than the settlement?
You can still owe the lender after a total loss because the insurer pays vehicle value, not loan balance. Gap coverage may pay some qualifying shortfall. Contact the lender and gap provider promptly. A high loan balance is not by itself evidence that the ACV calculation is wrong.
The most reliable answer comes from the specific vehicle and documentation rather than an internet average. Keep photos, estimates and policy or product paperwork when they affect the decision.
Should I accept the first check while disputing value?
That depends on the insurer, state rules and whether accepting payment releases the claim. Ask in writing whether the payment is undisputed partial payment or a full-and-final settlement. Do not sign a release you do not understand. For a significant dispute, seek state-specific advice.
You do not need to solve every variable yourself. A qualified repairer, glass shop, insurer or state regulator can confirm the details that are specific to your situation.
Conclusion
You can challenge a hail total-loss valuation by checking the insurer’s vehicle description, correcting mileage and option errors, documenting pre-loss condition and presenting genuinely comparable local vehicles. The goal is not to demand an arbitrary number; it is to show why the actual cash value should be different.
Your best next step is to verify the condition, documents or operating limits that control your specific case, then choose the least aggressive solution that fully addresses the problem. That approach gives you better odds of protecting the vehicle, your coverage and your budget at the same time.