If you are researching average payout for a car hail damage claim, the quickest answer is rarely the whole answer. The condition of the vehicle, the material involved and what you plan to do next can change the safest and most economical approach.
This guide focuses on the decisions that matter in real ownership rather than a one-size-fits-all shortcut. You will see what to inspect first, what can reasonably be handled yourself and where a professional estimate or inspection becomes the smarter move.
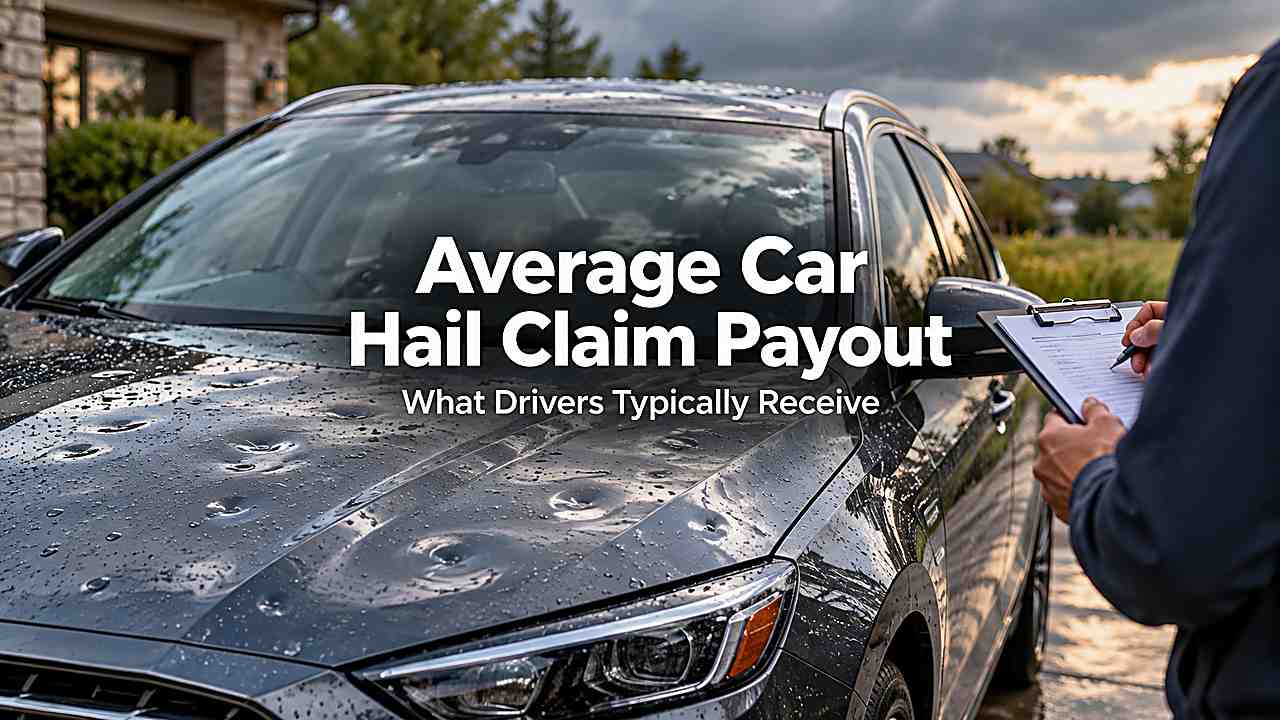
Current consumer-insurance sources often cite roughly $4,000 to $5,000 as a broad average auto hail claim benchmark, but your actual payout can be far lower or higher because repair cost, deductible, vehicle value, glass damage and total-loss status vary widely.
Use the average as context, not a promise
Several current sources cluster around the mid-thousands
Recent insurance-oriented sources commonly cite about $4,000 to $5,000 for an average vehicle hail claim, with some carrier information citing lower moderate-damage repair figures and other data showing much wider ranges. Those numbers reflect different populations and years. That is why a small test or inspection step should come before a more aggressive method. You get better results when you know what changed after each pass instead of repeating the same process blindly.
You should treat them as budgeting context rather than a guaranteed settlement. If your vehicle has previous bodywork, unusual materials or aftermarket protection, mention that before treatment or repair. Those details can change compatibility, labor and the point at which professional help becomes the safer choice.
Severe hail can move far beyond the average
Large hail can dent nearly every panel, crack glass and damage trim. Repairs that require panel replacement, painting and ADAS calibration can exceed $10,000. Good lighting and a clean surface make this judgment much easier. Dirt, gloss enhancers and shadows can hide defects or make harmless texture look worse than it really is.
Nationwide has cited repair ranges of roughly $3,000 to $13,000 excluding total losses in some claims data. The spread matters more than a single average. You should also consider the cost of creating a new problem. A conservative process that leaves a small cosmetic imperfection is often preferable to removing too much clear coat, damaging trim or disturbing a safety-related component.
Your payout is not the same thing as the repair estimate
The comprehensive deductible is normally subtracted
If a covered repair is estimated at $5,000 and your comprehensive deductible is $1,000, the insurer’s payment may be about $4,000 subject to policy terms and how payment is handled. That does not make the damage a $4,000 repair. The practical goal is a stable result, not a dramatic before-and-after created by excessive force. If the recommended method stops producing improvement, reassess rather than escalating automatically.
The repair still costs $5,000. Keeping estimate, deductible and payout separate prevents confusion. That is why a small test or inspection step should come before a more aggressive method. You get better results when you know what changed after each pass instead of repeating the same process blindly.
Prior damage and unrelated defects are not part of the new hail payment
The adjuster is estimating covered storm damage, not restoring every cosmetic issue the vehicle had beforehand. Existing dents, peeling paint or prior cracked glass can change what is payable. If your vehicle has previous bodywork, unusual materials or aftermarket protection, mention that before treatment or repair. Those details can change compatibility, labor and the point at which professional help becomes the safer choice.
Good pre-loss photos and maintenance records help when condition is disputed. Be accurate rather than trying to include unrelated damage. Good lighting and a clean surface make this judgment much easier. Dirt, gloss enhancers and shadows can hide defects or make harmless texture look worse than it really is.
Vehicle value can cap the claim through a total loss
A low-value car may be totaled even when the dents look repairable
If repair economics approach the vehicle’s pre-loss actual cash value under the applicable state and insurer method, the claim can shift from repair to total loss. The settlement then centers on vehicle value rather than the sum of every dent repair operation. You should also consider the cost of creating a new problem. A conservative process that leaves a small cosmetic imperfection is often preferable to removing too much clear coat, damaging trim or disturbing a safety-related component.
Deductible and lienholder interests can still affect the net payment. The practical goal is a stable result, not a dramatic before-and-after created by excessive force. If the recommended method stops producing improvement, reassess rather than escalating automatically.
A high-value vehicle can support a much larger repair
The same hail pattern on a newer luxury vehicle may justify a costly repair because the pre-loss value is higher. Aluminum panels, panoramic glass and advanced cameras can also increase repair cost. That is why a small test or inspection step should come before a more aggressive method. You get better results when you know what changed after each pass instead of repeating the same process blindly.
This is why averages do not predict your claim very well. Your vehicle’s exact configuration matters. If your vehicle has previous bodywork, unusual materials or aftermarket protection, mention that before treatment or repair. Those details can change compatibility, labor and the point at which professional help becomes the safer choice.
What changes the hail repair estimate most
Dent count, size and panel material drive PDR labor
A few shallow dents may stay below the deductible, while hundreds across several panels create many hours of work. Aluminum and difficult body lines can add labor. Good lighting and a clean surface make this judgment much easier. Dirt, gloss enhancers and shadows can hide defects or make harmless texture look worse than it really is.
Headliner and trim removal for access are part of the job. A reflection-light inspection may reveal more damage than outdoor photos. You should also consider the cost of creating a new problem. A conservative process that leaves a small cosmetic imperfection is often preferable to removing too much clear coat, damaging trim or disturbing a safety-related component.
Glass, paint and parts can transform a PDR claim
Cracked paint means refinishing. Broken windshields can require expensive glass and calibration. The practical goal is a stable result, not a dramatic before-and-after created by excessive force. If the recommended method stops producing improvement, reassess rather than escalating automatically.
Roof moldings, lamps and one-time-use clips add parts cost. A car with twenty dents and a damaged panoramic roof may cost more than one with a hundred small PDR-friendly dents. That is why a small test or inspection step should come before a more aggressive method. You get better results when you know what changed after each pass instead of repeating the same process blindly.
How to estimate your likely net payment
Get a qualified repair estimate before focusing on averages
A local body or PDR shop can document what the specific vehicle needs. Compare the repair total with your comprehensive deductible. If your vehicle has previous bodywork, unusual materials or aftermarket protection, mention that before treatment or repair. Those details can change compatibility, labor and the point at which professional help becomes the safer choice.
If the estimate barely exceeds the deductible, filing may produce little payment. If damage is extensive, notify the insurer promptly and allow the claim process to determine the covered scope. Good lighting and a clean surface make this judgment much easier. Dirt, gloss enhancers and shadows can hide defects or make harmless texture look worse than it really is.
Review the valuation report if the car is totaled
A total-loss settlement should reflect accurate trim, mileage, options and pre-loss condition. Check comparable vehicles and factual inputs. You should also consider the cost of creating a new problem. A conservative process that leaves a small cosmetic imperfection is often preferable to removing too much clear coat, damaging trim or disturbing a safety-related component.
The national average hail claim is irrelevant once your claim becomes a valuation question. Use your actual market evidence instead. The practical goal is a stable result, not a dramatic before-and-after created by excessive force. If the recommended method stops producing improvement, reassess rather than escalating automatically.
Why published averages differ
Sources may be measuring repair cost, insurer payment or claim severity
One article may quote what repairs cost before deductible, while another may describe average insurer payments. Data can also mix moderate and severe storms or different vehicle years. That is why a small test or inspection step should come before a more aggressive method. You get better results when you know what changed after each pass instead of repeating the same process blindly.
Ask what the number represents before comparing it with your check. A precise-looking figure without population and year can be misleading. If your vehicle has previous bodywork, unusual materials or aftermarket protection, mention that before treatment or repair. Those details can change compatibility, labor and the point at which professional help becomes the safer choice.
Storm geography changes the mix of claims
Regions with frequent large hail, newer vehicle fleets or higher labor rates can produce larger average losses. Catastrophe years can also shift data sharply. Good lighting and a clean surface make this judgment much easier. Dirt, gloss enhancers and shadows can hide defects or make harmless texture look worse than it really is.
Your local shop rates and vehicle mix may not resemble a national sample. Use local estimates for decisions and averages only for perspective. You should also consider the cost of creating a new problem. A conservative process that leaves a small cosmetic imperfection is often preferable to removing too much clear coat, damaging trim or disturbing a safety-related component.
Frequently Asked Questions
These questions address the issues that most often come up when you are dealing with average payout for a car hail damage claim. They also clarify where a general rule stops being useful and the condition of the specific vehicle, policy, surface or repair has to decide the answer.
Is $5,000 a normal hail claim?
It falls within commonly cited current auto-hail averages, but normal covers a wide range. A few dents may cost under $1,000, while severe multi-panel damage can exceed $10,000 or total the vehicle. The practical goal is a stable result, not a dramatic before-and-after created by excessive force. If the recommended method stops producing improvement, reassess rather than escalating automatically.
Deductible also affects the payment you receive. The repair estimate for your car is more useful than the national average. That is why a small test or inspection step should come before a more aggressive method. You get better results when you know what changed after each pass instead of repeating the same process blindly.
Does the deductible come out of the average payout?
Published figures are not always defined the same way, so some describe claim severity or repair cost while others discuss insurer payment. On your own claim, comprehensive coverage typically applies the deductible according to the policy. If your vehicle has previous bodywork, unusual materials or aftermarket protection, mention that before treatment or repair. Those details can change compatibility, labor and the point at which professional help becomes the safer choice.
Ask whether a quoted statistic is gross damage or net payment. Do not assume every average already accounts for deductibles. Good lighting and a clean surface make this judgment much easier. Dirt, gloss enhancers and shadows can hide defects or make harmless texture look worse than it really is.
What if the repair estimate is below my deductible?
The insurer would generally have little or nothing to pay on that covered loss. You can still document the damage and decide whether to repair privately. You should also consider the cost of creating a new problem. A conservative process that leaves a small cosmetic imperfection is often preferable to removing too much clear coat, damaging trim or disturbing a safety-related component.
Filing practices and future underwriting effects vary by insurer and state. If you are unsure, discuss the estimate with your carrier before authorizing work. The practical goal is a stable result, not a dramatic before-and-after created by excessive force. If the recommended method stops producing improvement, reassess rather than escalating automatically.
Can a hail claim pay more than the car is worth?
Normally, an insurer will evaluate total loss rather than pay unlimited repair cost above the vehicle’s economic value. State rules and policy provisions affect the threshold and calculation. That is why a small test or inspection step should come before a more aggressive method. You get better results when you know what changed after each pass instead of repeating the same process blindly.
If totaled, settlement focuses on actual cash value rather than the full repair estimate. Your deductible may still apply. If your vehicle has previous bodywork, unusual materials or aftermarket protection, mention that before treatment or repair. Those details can change compatibility, labor and the point at which professional help becomes the safer choice.
Why did my neighbor get a larger hail check for a similar car?
Damage can differ in dent depth, panel count, paint cracking, glass, material and access even when two cars sat next to each other. Deductibles and vehicle options may also differ. Good lighting and a clean surface make this judgment much easier. Dirt, gloss enhancers and shadows can hide defects or make harmless texture look worse than it really is.
One claim may include a supplement that the other has not received yet. Compare written estimates rather than check amounts alone. You should also consider the cost of creating a new problem. A conservative process that leaves a small cosmetic imperfection is often preferable to removing too much clear coat, damaging trim or disturbing a safety-related component.
Conclusion
Current consumer-insurance sources often cite roughly $4,000 to $5,000 as a broad average auto hail claim benchmark, but your actual payout can be far lower or higher because repair cost, deductible, vehicle value, glass damage and total-loss status vary widely. The important part is applying that answer to the actual condition in front of you rather than forcing a universal rule onto every vehicle.
Your next step should be the lowest-risk action that gives you better information: inspect carefully, test a small area, verify the policy or product instructions, compare current market evidence or obtain a qualified professional assessment. That keeps the decision practical and protects the value of the vehicle.